SGLI to VGLI: Deadlines, Cost and How to Convert (Free Calculator)
Education only, not legal or financial advice. Not affiliated with the VA or DoD. Numbers checked against official sources on October 28, 2026. Disclosures.
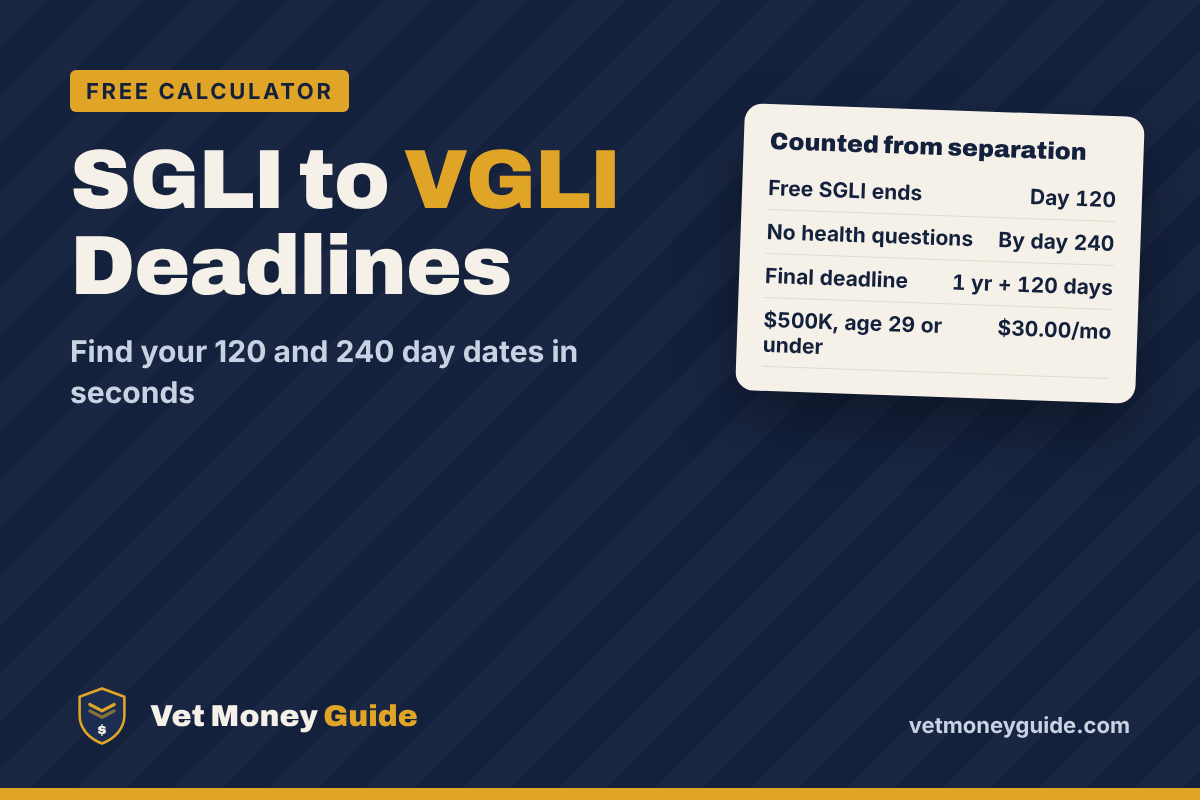
Going from SGLI to VGLI comes down to three dates, all counted from the day you leave the military: your SGLI stays free for 120 days, you can apply for VGLI with no health questions for 240 days, and the final deadline to apply is 1 year and 120 days. Miss the last one and VGLI is gone for good.
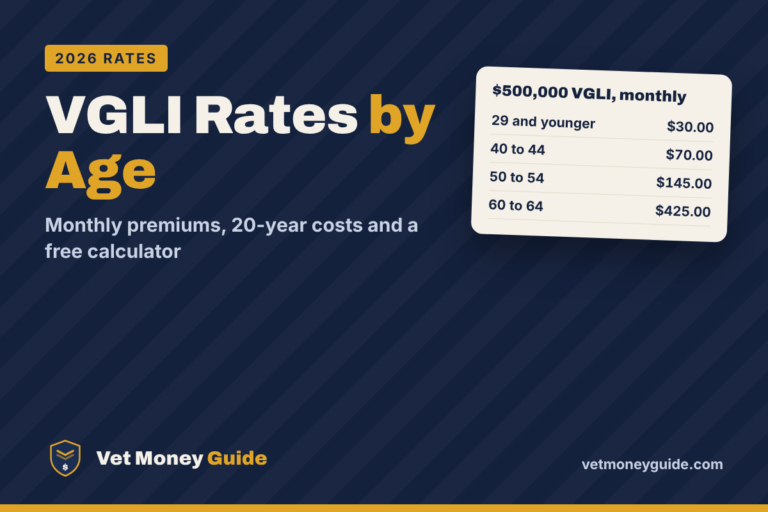
VGLI (Veterans’ Group Life Insurance) lets you keep the same coverage you had under SGLI, from $10,000 up to $500,000, as a civilian. The catch is the price: VGLI premiums go by age and climb every five years. Under VA’s rates effective July 1, 2025, $500,000 of VGLI costs $30.00 a month at 29 and younger, $70.00 at 40 to 44 and $145.00 at 50 to 54.
Below: a free calculator that turns your separation date into real calendar dates, how to apply, what to do if you missed the window, VALife for veterans with a VA rating, and an honest look at VGLI next to private term life.
Quick answer
- Day 120: free SGLI coverage ends. The earliest VGLI can start is day 121.
- Day 240: last day to apply for VGLI with no health review.
- 1 year and 120 days: final deadline. Between day 241 and this date you must send evidence of good health.
- Coverage: $10,000 to $500,000, never more than the SGLI you had when you left.
- Cost for $500,000: $30.00 a month at 29 and younger, $70.00 at 40 to 44, $145.00 at 50 to 54, $425.00 at 60 to 64.
In this guide
Your three SGLI to VGLI deadlines (free calculator)
Enter the date you left the military. The calculator shows the three dates in plain calendar form, how many days you have left on each, and lets you save them to your phone’s calendar with reminders 30 and 7 days before each one.
Free VGLI deadline calculator
Enter the date you left the military. You get your three SGLI to VGLI dates, counted the way VA.gov states the rules.
Rules from VA.gov, checked October 28, 2026. Education only. Nothing you type is stored or sent; the calendar file is made in your browser.
Here is what each date means, straight from VA.gov:
- Day 120, free SGLI ends. Your SGLI keeps covering you for 120 days from the date you leave, at no cost. VA’s premium holiday FAQ says the earliest a new VGLI policy can take effect is the 121st day after separation. Day 120 is also the last day to convert SGLI to an individual permanent policy (such as whole life) with a participating insurer without proof of good health.
- Day 240, the no-health-questions window closes. Apply for VGLI within 240 days of leaving and VA does not review your health. This is the date that matters most.
- 1 year and 120 days, the final deadline. You can still apply after day 240, but you must submit evidence that you are in good health. After this date, the door is closed.
Watch out: the calculator counts calendar days from your separation date the way VA’s rules read. The Office of Servicemembers’ Group Life Insurance (OSGLI), which runs VGLI for VA, has the final word on your dates. Treat every date as a “no later than” and apply well before it.
Two special cases. If you are totally disabled when you leave, the SGLI Disability Extension (form SGLV 8715) can keep your SGLI free for up to 2 years; confirm your VGLI dates with OSGLI, because they may not match the calculator. And part-time Guard or Reserve members covered by SGLI may qualify for VGLI if an on-duty injury or disability kept them from getting standard premium rates.
How to convert SGLI to VGLI, step by step
There is no automatic switch. SGLI simply ends, and VGLI starts only if you apply and pay. As an Army veteran, I’d put this on the same out-processing list as your final DD-214 review: it takes minutes, and the deadline is easy to lose in the move.
- Confirm your separation date and SGLI amount. Your separation date starts every clock. Your SGLI amount is the most VGLI you can get.
- Apply online through OSGLI. VA.gov links to the OSGLI application on Prudential’s website. Prudential runs OSGLI for VA.
- Or apply by mail. Fill out the Application for Veterans’ Group Life Insurance (SGLV 8714) and mail it to OSGLI, PO Box 41618, Philadelphia, PA 19176-9913. Keep a copy and note the date you mailed it.
- Name your beneficiaries. Do it in the online portal or on the VGLI Beneficiary Designation form (SGLV 8721). Make sure the names and shares are what you want today.
- Pay the first premium. VA’s FAQ is clear that the first premium is always required. After that, you can use AutoPay or have premiums taken from military retired pay or VA disability compensation.
- Follow up. If you haven’t heard back within a few weeks, contact OSGLI (osgli.osgli@prudential.com) before your day-240 date, not after.
Tip: apply inside the first 120 days. You still get the free SGLI months, VGLI can start the day after they end, and you never touch the health-review rules.
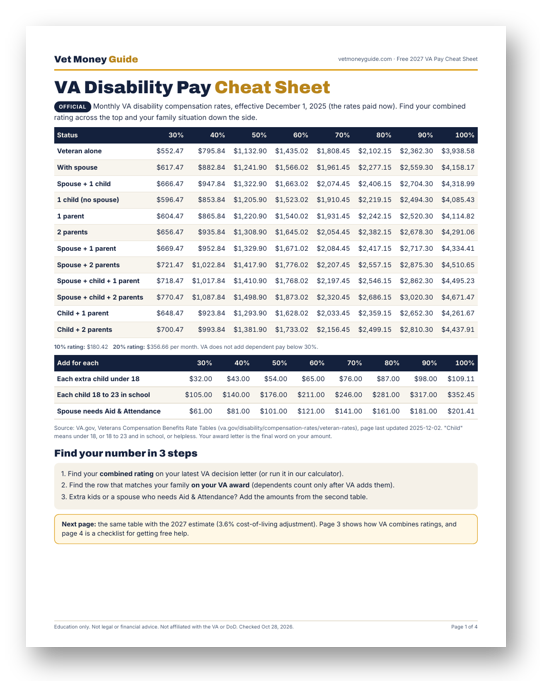
Free: the 2027 VA Pay Cheat Sheet
Every VA disability rate on one page, the 2027 estimate with the 3.6% COLA, the combined rating math, and a checklist for free VSO help. 4 printable pages.
How much VGLI coverage you can get
VGLI runs from $10,000 to $500,000, but it is capped at the SGLI coverage you had when you left. Full-time SGLI tops out at $500,000 and is sold in $50,000 steps, so if you kept full SGLI, you can carry $500,000 into VGLI.
You can take less than your SGLI amount if you want a lower premium. You can also add coverage later: VA lets you increase VGLI by $25,000 one year after you get it, and then every 5 years, up to $500,000, until age 60. VA’s FAQ notes this $25,000 increase is not automatic. You have to elect it.
VGLI is renewable term insurance. It has no cash value and no loan value, and it lasts as long as you keep paying the premium. Premiums depend only on age and coverage, not on gender or tobacco use.
What VGLI costs
These are VA’s monthly VGLI premiums effective July 1, 2025, for three common coverage amounts. Your rate goes up as you move into each older age bracket.
| Age bracket | $100,000 | $250,000 | $500,000 |
|---|---|---|---|
| 29 and younger | $6.00 | $15.00 | $30.00 |
| 30 to 34 | $8.00 | $20.00 | $40.00 |
| 35 to 39 | $10.00 | $25.00 | $50.00 |
| 40 to 44 | $14.00 | $35.00 | $70.00 |
| 45 to 49 | $19.00 | $47.50 | $95.00 |
| 50 to 54 | $29.00 | $72.50 | $145.00 |
| 55 to 59 | $50.00 | $125.00 | $250.00 |
| 60 to 64 | $85.00 | $212.50 | $425.00 |
| 65 to 69 | $138.00 | $345.00 | $690.00 |
| 70 to 74 | $215.00 | $537.50 | $1,075.00 |
| 75 to 79 | $385.00 | $962.50 | $1,925.00 |
| 80 and older | $440.00 | $1,100.00 | $2,200.00 |
Read across the bottom rows and you see the problem. The same $500,000 that costs $30.00 a month in your 20s costs $425.00 a month at 60 to 64. VGLI is cheap when you are young and gets expensive fast after 55.
See your total VGLI cost over 20 years
The free VGLI cost calculator takes your age and coverage and adds up every premium, bracket by bracket. You can also type in a real private term quote to compare the totals.
Open the VGLI rates and cost calculatorTip: VA is running a VGLI premium holiday. Eligible VGLI policyholders pay no premiums from November 1, 2026 through January 31, 2027, and coverage continues. New VGLI policies that take effect before January 1, 2027 may qualify for part of it, but the first premium is always due. Details are on the VGLI rates page.
What happens if you miss the deadline
It depends on which deadline you missed.
- Missed day 240, still inside 1 year and 120 days: you can still apply, but you have to send evidence of good health. If your health is fine, apply right away. If you have conditions that could lead to a denial, apply anyway and look at the backstops below at the same time.
- Missed 1 year and 120 days: VGLI is no longer open to you. Your realistic options are VALife, if you have any VA service-connected rating, and private life insurance.
- Had VGLI and it lapsed: that is a different situation. VA has an Application for Reinstatement of VGLI Coverage (SGLV 180). Contact OSGLI quickly.
Watch out: don’t let SGLI end without a plan. Once free SGLI runs out on day 120, you have no SGLI or VGLI coverage until a VGLI policy starts.
VALife: the backstop if you have a VA rating
VALife (Veterans Affairs Life Insurance) is VA’s guaranteed acceptance whole life insurance for veterans with service-connected disabilities. Here are the rules on VA.gov as of October 2026:
- Who: veterans age 80 or younger with any VA service-connected rating, even 0%. There is no time limit to apply after you get the rating. (At 81 or older, you qualify only if you applied for compensation before 81, got a rating for that condition after 81, and apply within 2 years of the rating notice.)
- How much: up to $40,000 of whole life coverage, in $10,000 steps.
- No health questions: if you are eligible, VA approves the application.
- 2-year waiting period: full coverage starts 2 years after you apply, and you pay premiums during that time. If you die during the waiting period, your beneficiaries get the premiums you paid plus interest (VA lists 4.23% for 2026 deaths).
- Premiums: set by your age when you apply and your coverage amount, and they don’t go up while you keep the policy. Cash value starts building 2 years after approval. VALife has no loans and no premium waivers.
VALife is not a replacement for $500,000 of VGLI. It is a floor: $40,000 you can always get, no matter your health. VA’s VALife page doesn’t say whether you can hold VALife and VGLI at the same time, so ask the VA Life Insurance Center before you count on both.
No rating yet? A VA-accredited Veterans Service Officer (VSO) can help you file a disability claim for free. Don’t pay an unaccredited “claim consultant.” If you want to see what a rating pays, the free VA disability calculator shows the monthly amount.
VGLI vs private term life
VA’s own comparison page lays out the trade. The short version:
| VGLI | Private term life | |
|---|---|---|
| Health questions | None if you apply within 240 days | May require a health review or a medical exam |
| What sets the price | Age and coverage only | Age, health, coverage, term length, and often gender and tobacco use |
| Premium over time | Goes up every 5 years with age | Level term: the same premium for the whole term |
| How long it lasts | For life, as long as you pay | A fixed term, usually 10 to 30 years, then it ends |
| Coverage limit | $500,000, capped at your SGLI amount | Set by the insurer and your underwriting |
Where private term can win: if you are young, healthy and don’t use tobacco, a level premium locked for 20 or 30 years may cost less in total than VGLI’s rising brackets. Where VGLI wins: if you have health problems, including service-connected conditions that private insurers ask about, or if you need coverage past the end of any term you could buy.
We won’t quote you private prices here, because they depend on your health answers, and an online estimate is not an offer. The fair test is simple: get a real quote for the same coverage and the same number of years, multiply the monthly premium by 12 and by the years, and compare it with your VGLI total from the VGLI cost calculator.
Compare private term life quotes
Before your day-240 date, get two or three level-term quotes for the same coverage you would keep in VGLI and the same number of years. Ask each insurer whether the price is final after underwriting, whether a medical exam is required, and whether the policy can be converted later. Then put the numbers side by side with VGLI.
Tip: you don’t have to choose on day one. Apply for VGLI inside 240 days, shop private term at the same time, and drop VGLI only after the private policy is approved and in force. That way your family is never uncovered.
One more option most people miss: VA says you can convert VGLI to an individual permanent policy (such as whole life) with a participating insurer at any time, at standard rates, without proof of good health. You need a VGLI Conversion Notice from OSGLI, and term, variable and universal policies aren’t eligible.
Should you convert SGLI to VGLI?
For most people leaving the service, applying for VGLI inside 240 days is the safe move, even if you plan to replace it. Run through this list:
- Do you have any health condition, service-connected or not, that an insurer might ask about? VGLI inside 240 days asks nothing.
- Does someone depend on your income: a spouse, kids, a mortgage? Then a gap in coverage is a real risk.
- Do you already have a new job with group life insurance? Check how much it pays and whether it ends when the job does.
- How many years do you need coverage? Until the kids are grown or the house is paid off is a common target.
- Have you priced private term for those years? Compare the totals, not the first month’s premium.
- Do you have a VA rating? Then VALife’s $40,000 is available to you no matter what.
If you answered yes to the health question, VGLI’s guaranteed acceptance is worth a lot. If you are young and healthy with a clear coverage end date, private term deserves a hard look, and VGLI can bridge you until it’s approved.
VGLI Rates by Age: Full Chart, 20-Year Costs and Calculator
VA Disability Calculator 2027: Combined Rating + Dependents
FAQ
How long do you have to convert SGLI to VGLI?
You have 1 year and 120 days from the date you leave the military. Apply within the first 240 days and VA asks no health questions. After day 240, you must send evidence of good health.
Should I convert SGLI to VGLI?
If you have any health issues or need coverage for life, yes: inside 240 days VGLI is guaranteed. If you are young and healthy, compare a level-term quote first, but apply for VGLI anyway so you are covered while you shop. $500,000 of VGLI is $30.00 a month at 29 and younger.
Is VGLI term or whole life?
VGLI is renewable term life insurance. It has no cash value or loan value, and it renews every 5 years for life as long as you pay. VALife, VA’s other program, is whole life, capped at $40,000.
How much is VGLI per month?
It depends on age and coverage. Under VA’s rates effective July 1, 2025, $250,000 costs $15.00 a month at 29 and younger, $35.00 at 40 to 44 and $125.00 at 55 to 59. Every $10,000 of coverage costs $0.60 a month at 29 and younger.
Can I get VGLI as a veteran years after I got out?
Only if you are still within 1 year and 120 days of leaving the military. VA’s eligibility list also covers events like release from the Ready Reserve or Guard, so ask OSGLI if that applies to you. Past your deadline, look at VALife (any VA rating, age 80 or younger, up to $40,000) or private coverage.
Does SGLI to VGLI happen automatically?
No. SGLI ends 120 days after you leave, and VGLI starts only if you apply through OSGLI and pay the first premium. The earliest VGLI can take effect is day 121.
Sources (checked October 28, 2026)
- VA.gov, Veterans’ Group Life Insurance (VGLI): deadlines, coverage, how to apply, rates effective July 1, 2025 (page updated October 13, 2026)
- VA.gov, Servicemembers’ Group Life Insurance (SGLI): 120 days free coverage, Disability Extension, conversion options (page updated October 14, 2026)
- VA, VGLI Premium Holiday FAQs: earliest VGLI effective date, first premium, payment methods (updated September 15, 2026)
- VA, Application for Veterans’ Group Life Insurance (SGLV 8714)
- VA.gov, Veterans Affairs Life Insurance (VALife) (page updated October 13, 2026)
- My Air Force Benefits, VALife fact sheet (reviewed January 29, 2026)
- VA.gov, Compare VGLI to other life insurance options (updated September 9, 2026)
- VA, Find a VA-accredited representative