VGLI Rates by Age (2026 Chart): Monthly Premiums, 20-Year Costs and Calculator
Education only, not legal or financial advice. Not affiliated with the VA or DoD. Numbers checked against official sources on October 28, 2026. Disclosures.
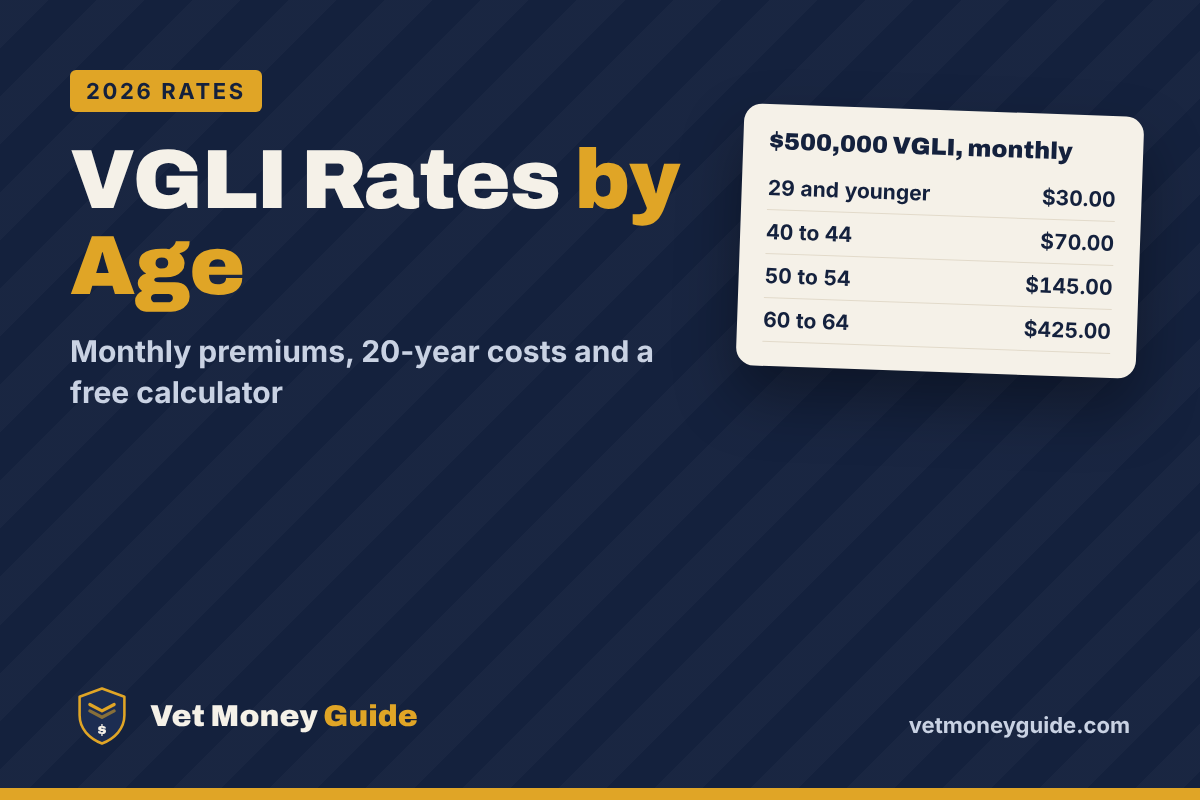
VGLI rates depend on only two things, your age bracket and your coverage amount, and every $10,000 of coverage costs from $0.60 a month at 29 and younger to $44.00 a month at 80 and older. For the full $500,000, that is $30.00 a month in your 20s, $70.00 at 40 to 44, $145.00 at 50 to 54 and $425.00 at 60 to 64.
These are VA’s current Veterans’ Group Life Insurance premiums, effective July 1, 2025, copied from VA.gov and checked on October 28, 2026. Below you get the full chart, a free calculator that adds up what VGLI costs you over 5 to 30 years, worked 20-year examples, the premium holiday running November 1, 2026 to January 31, 2027, and an honest way to compare VGLI with private term life.
Quick answer
- $500,000 of VGLI per month: $30.00 (29 and younger), $70.00 (40 to 44), $145.00 (50 to 54), $425.00 (60 to 64).
- Per $10,000: $0.60 a month at 29 and younger, $1.40 at 40 to 44, $8.50 at 60 to 64.
- Rates rise every 5 years as you move into the next age bracket. Gender and tobacco use don’t count.
- 20 years of $500,000 starting at 25: $11,400.00 in total. Starting at 40: $33,600.00. Starting at 50: $90,600.00.
- Premium holiday: no VGLI premiums due November 1, 2026 through January 31, 2027 for eligible policyholders.
VGLI rate chart by age (2026)
This is VA’s monthly VGLI premium table, effective July 1, 2025, and still current when we checked VA.gov on October 28, 2026. VA’s page lists every $10,000 step from $10,000 to $500,000. We show six columns; every figure below is exactly as VA prints it.
| Age bracket | Per $10,000 | $50,000 | $100,000 | $250,000 | $400,000 | $500,000 |
|---|---|---|---|---|---|---|
| 29 and younger | $0.60 | $3.00 | $6.00 | $15.00 | $24.00 | $30.00 |
| 30 to 34 | $0.80 | $4.00 | $8.00 | $20.00 | $32.00 | $40.00 |
| 35 to 39 | $1.00 | $5.00 | $10.00 | $25.00 | $40.00 | $50.00 |
| 40 to 44 | $1.40 | $7.00 | $14.00 | $35.00 | $56.00 | $70.00 |
| 45 to 49 | $1.90 | $9.50 | $19.00 | $47.50 | $76.00 | $95.00 |
| 50 to 54 | $2.90 | $14.50 | $29.00 | $72.50 | $116.00 | $145.00 |
| 55 to 59 | $5.00 | $25.00 | $50.00 | $125.00 | $200.00 | $250.00 |
| 60 to 64 | $8.50 | $42.50 | $85.00 | $212.50 | $340.00 | $425.00 |
| 65 to 69 | $13.80 | $69.00 | $138.00 | $345.00 | $552.00 | $690.00 |
| 70 to 74 | $21.50 | $107.50 | $215.00 | $537.50 | $860.00 | $1,075.00 |
| 75 to 79 | $38.50 | $192.50 | $385.00 | $962.50 | $1,540.00 | $1,925.00 |
| 80 and older | $44.00 | $220.00 | $440.00 | $1,100.00 | $1,760.00 | $2,200.00 |
Need an amount not shown? Every column is a straight multiple of the $10,000 rate, so you can work it out yourself:
Example: $300,000 of VGLI at age 47
Age 47 is in the 45 to 49 bracket: $1.90 per $10,000.
$300,000 / $10,000 = 30 units
30 x $1.90 = $57.00 a month
Two things VA says about these rates: they depend only on age and coverage, not on gender or tobacco use, and coverage lasts for life as long as you keep paying. Your VGLI can’t be more than the SGLI you had when you left, up to $500,000.
VGLI cost over time calculator
The monthly number is only half the story. Pick your age, coverage and how many years you’ll keep VGLI, and the calculator shows what you pay in every age bracket and the total. If you already have a private term quote, type it in to compare the totals.
Free VGLI cost over time calculator
Pick your age and coverage. See what VGLI costs each month in every VA age bracket, and the total you would pay over the years you choose.
VGLI rates from VA.gov (effective July 1, 2025), checked October 28, 2026. Education only. Nothing you type is stored or sent.
The calculator counts each year of age at its bracket rate, 12 months a year. VA describes VGLI as having premium rates “that increase every five years based on age,” but its rate page doesn’t spell out the exact month the change hits your bill. Your OSGLI statement shows it. If your increase lands a few months later than the calculator assumes, your real total will be a little lower.
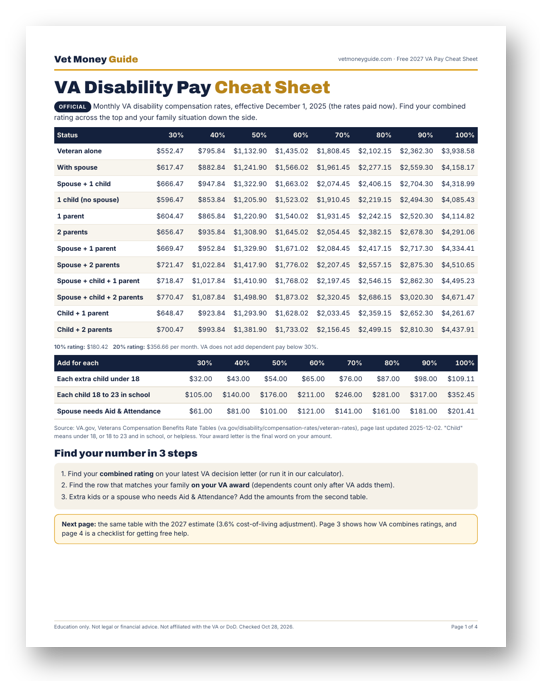
Free: the 2027 VA Pay Cheat Sheet
Every VA disability rate on one page, the 2027 estimate with the 3.6% COLA, the combined rating math, and a checklist for free VSO help. 4 printable pages.
How VGLI premiums rise every 5 years
VGLI is renewable term insurance. VA’s comparison page says it can be renewed every 5 years for the rest of your life as long as you keep paying. Each new bracket brings a higher premium. Here is what each step does to $500,000 of coverage:
| Moving into | New monthly premium | Increase per month |
|---|---|---|
| 30 to 34 | $40.00 | +$10.00 |
| 35 to 39 | $50.00 | +$10.00 |
| 40 to 44 | $70.00 | +$20.00 |
| 45 to 49 | $95.00 | +$25.00 |
| 50 to 54 | $145.00 | +$50.00 |
| 55 to 59 | $250.00 | +$105.00 |
| 60 to 64 | $425.00 | +$175.00 |
| 65 to 69 | $690.00 | +$265.00 |
| 70 to 74 | $1,075.00 | +$385.00 |
| 75 to 79 | $1,925.00 | +$850.00 |
| 80 and older | $2,200.00 | +$275.00 |
Through your 30s and 40s the steps are small: $10 to $25 a month. From 50 on they get big. The step into 55 to 59 adds $105.00 a month, and by 60 to 64 you pay more than 14 times what the same coverage cost at 29 ($425.00 vs $30.00).
Watch out: these are today’s rates. VA sets VGLI premiums, and this table has been in effect since July 1, 2025. Plan with these numbers, but check VA.gov once a year.
VGLI premium holiday: Nov 1, 2026 to Jan 31, 2027
Tip: Update as of October 28, 2026. VA is giving eligible VGLI policyholders a three-month premium holiday: no premiums are due for November 2026, December 2026 or January 2027. Coverage keeps going. Regular premiums restart in February 2027.
VA announced the holiday on September 16, 2026, saying more than 457,000 veterans participate in VGLI and the break will save them nearly $150 million. The details, from VA’s premium holiday FAQ (updated September 15, 2026):
- Who gets it: VGLI policyholders whose coverage is active on November 1, 2026. You don’t need to do anything. If you cancel, or your coverage lapses, on or before October 31, 2026, you don’t get it.
- New policies: coverage effective before November 1, 2026 gets all three months; effective in November gets December and January; effective in December gets January; effective January 1, 2027 or later gets none. Your first premium is always due. Since SGLI runs 120 days after separation, the earliest a new VGLI policy can start is day 121.
- AutoPay and deductions: AutoPay skips the holiday months. Deductions from military retired pay or VA disability compensation pause and then resume.
- Bank bill pay: you have to stop it yourself effective November 1, 2026 and restart it effective February 1, 2027.
- Paid ahead? If you paid quarterly or yearly, the credit shows up on your next bill automatically.
- Behind on payments? Past-due amounts still have to be paid, or coverage lapses after the holiday.
- Not included: SGLI, FSGLI, TSGLI, VALife and S-DVI.
What three months are worth on $500,000 of coverage, using the chart above: $90.00 at 29 and younger, $210.00 at 40 to 44, $435.00 at 50 to 54 and $1,275.00 at 60 to 64. If your age increase lands during the holiday, VA’s FAQ says the higher premium is covered too.
What VGLI costs over 20 years: worked examples
Twenty years is a common planning window: long enough to cover kids at home or most of a mortgage. Here is the full math for one case, then a table of others, all computed from VA’s rates with the calculator above.
Separating at 25 with $500,000, kept for 20 years (ages 25 to 44)
Ages 25 to 29: $30.00 x 60 months = $1,800.00
Ages 30 to 34: $40.00 x 60 months = $2,400.00
Ages 35 to 39: $50.00 x 60 months = $3,000.00
Ages 40 to 44: $70.00 x 60 months = $4,200.00
Total: $1,800.00 + $2,400.00 + $3,000.00 + $4,200.00 = $11,400.00
Average: $11,400.00 / 240 months = $47.50 a month
| Starting age and coverage | Monthly in year 1 | Monthly in year 20 | 20-year total |
|---|---|---|---|
| 25, $500,000 | $30.00 | $70.00 | $11,400.00 |
| 35, $400,000 | $40.00 | $116.00 | $17,280.00 |
| 40, $500,000 | $70.00 | $250.00 | $33,600.00 |
| 45, $250,000 | $47.50 | $212.50 | $27,450.00 |
| 50, $500,000 | $145.00 | $690.00 | $90,600.00 |
| 55, $100,000 | $50.00 | $215.00 | $29,280.00 |
The lesson is in the starting age. The same $500,000 for the same 20 years costs $11,400.00 if you start at 25, $33,600.00 if you start at 40, and $90,600.00 if you start at 50. A 55-year-old keeping just $100,000 for 20 years pays $29,280.00, more than a 25-year-old pays for five times the coverage.
VGLI rates vs private term life
VGLI’s rising brackets are exactly where a private level-term policy can come out ahead, but not for everyone. We won’t print private prices here: they depend on your health answers, and a number from an ad is not an offer. What we can do is show you how the comparison works.
What drives a private term quote
- Your health. VA’s comparison page notes private insurers may require a health review or medical exam, and health conditions can affect eligibility. That includes service-connected conditions.
- Gender and tobacco use. VA notes private insurers often price on both. VGLI uses neither.
- Your age when you buy. With level term, the premium is set at the start and stays the same for the whole term.
- Coverage amount and term length. VA says private terms usually run 10 to 30 years. When the term ends, the coverage ends.
How to compare fairly
- Decide the coverage and the number of years you actually need.
- Get your VGLI total for those years from the calculator above.
- Get two or three level-term quotes for the same coverage and term. Answer the health questions honestly, or the quote means nothing.
- Multiply each monthly quote by 12 and by the years. Type it into the calculator’s quote box to see the difference.
- Then weigh what the totals don’t show: VGLI keeps going after year 20 if you still need it; a term policy stops.
Compare private term life quotes
Get level-term quotes for the same coverage and number of years you would keep VGLI. Ask whether the price is final after underwriting, whether you need a medical exam, and whether the policy can be converted later. Then run the monthly figure through the VGLI cost calculator above to compare the totals.
Tip: if you just separated, apply for VGLI inside 240 days (no health questions) and shop for private term at the same time. Cancel VGLI only after the private policy is approved and in force. Our SGLI to VGLI guide has a free deadline calculator for your dates.
Rough rule of thumb from the math: the younger and healthier you are, and the shorter the time you need coverage, the better private term tends to look next to VGLI’s rising brackets. The older you are, or the more health history you have, the more VGLI’s no-questions acceptance is worth. Run your own numbers rather than trusting any rule.
Ways to keep VGLI affordable
- Carry only what you need. You can take less than your SGLI amount, and VA’s FAQ shows you can ask to decrease coverage later. Every $10,000 you drop saves the per-$10,000 rate in the chart.
- Plan for the step-ups. Mark the year you enter each new bracket. The jumps at 50, 55 and 60 are the ones that hurt.
- Pay the easy way. VA’s FAQ lists AutoPay and deductions from military retired pay or VA disability compensation. Both keep you from missing a payment and lapsing.
- Know your backstop. With any VA service-connected rating, VALife offers up to $40,000 of whole life with guaranteed acceptance, a 2-year waiting period, and premiums that stay fixed.
As an Army veteran, my advice is simple: decide how many years your family needs coverage, then let the totals, not the first month’s premium, make the call.
SGLI to VGLI: Deadlines, Cost and How to Convert (Free Calculator)
VA Disability Calculator 2027: Combined Rating + Dependents
FAQ
How much is VGLI per month?
It depends on your age bracket and coverage. $500,000 costs $30.00 a month at 29 and younger, $50.00 at 35 to 39, $95.00 at 45 to 49 and $250.00 at 55 to 59, under VA’s rates effective July 1, 2025. Smaller amounts scale down: $100,000 is one fifth of those figures.
Do VGLI rates increase with age?
Yes. VA says VGLI premiums increase every five years based on age. For $500,000, the monthly premium goes from $30.00 at 29 and younger to $425.00 at 60 to 64 and $2,200.00 at 80 and older.
Is VGLI worth it?
It’s worth it if you need coverage and have health issues, or need coverage for life, because inside 240 days of leaving there are no health questions. If you are young and healthy, compare a real level-term quote: $500,000 of VGLI from 25 to 44 totals $11,400.00, so put any private quote against that number.
Do VGLI rates depend on smoking or gender?
No. VA states VGLI premiums depend only on age and don’t vary by gender or tobacco use. Private insurers often price on both, according to VA’s comparison page.
Who qualifies for the VGLI premium holiday in 2026?
VGLI policyholders with coverage active on November 1, 2026, with no action needed. No premiums are due for November, December and January, and payments restart in February 2027. New policies effective in November or December 2026 get the remaining months, but the first premium is always due.
Sources (checked October 28, 2026)
- VA.gov, Veterans’ Group Life Insurance (VGLI): premium rates effective July 1, 2025, coverage rules, premium holiday notice (page updated October 13, 2026)
- VA, VGLI Premium Holiday FAQs (updated September 15, 2026)
- VA News, VA announces insurance premium holiday that will save Veterans nearly $150 million (September 16, 2026)
- VA.gov, Compare VGLI to other life insurance options (updated September 9, 2026)
- VA.gov, Servicemembers’ Group Life Insurance (SGLI) (page updated October 14, 2026)
- VA.gov, Veterans Affairs Life Insurance (VALife) (page updated October 13, 2026)